

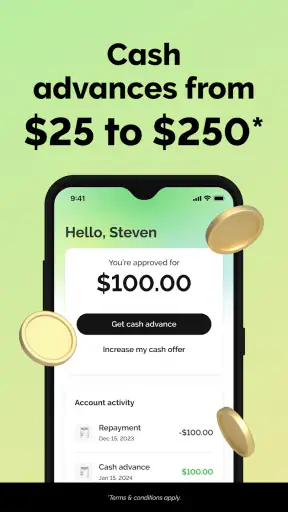
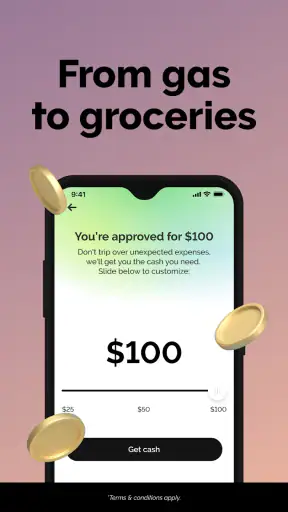
When an unexpected bill lands between paychecks, the appeal of Grant Cash Advance is easy to understand. It is a finance app from Kikoff Inc. built around getting cash quickly, with a straightforward promise: no credit check and no interest. I approached it as a short-term emergency tool rather than a replacement for regular budgeting, and that distinction shaped my experience. The app feels most useful when the amount needed is modest, the repayment plan is clear, and I already know exactly how the money will fit into my next budget.
It is free to download and available to everyone by age rating, which removes two common barriers when someone is looking for help in a hurry. The app has also attracted a substantial audience, with more than a million installs and an average rating of 4.8 from roughly 135 thousand ratings. Those figures suggest that many people find the service approachable, although popularity should not be confused with suitability for every financial situation.
How Grant Cash Advance fits into real financial emergencies
The strongest use case is a temporary cash-flow gap. Imagine a utility payment is due before payday, a car needs a minor repair, or a grocery purchase cannot wait until the next deposit. In that situation, a cash advance can be less disruptive than missing a payment or using a high-cost credit option. I would still begin by checking whether the expense can be postponed, reduced, or covered from savings, but the app makes sense when those choices are not available.
The important word is “temporary.” This is not the kind of app I would use to cover a recurring shortfall every month. If rent, food, or transportation regularly exceed income, repeated advances can hide the underlying problem and make the next pay cycle feel even tighter. The no-interest positioning is attractive, but repayment still affects the money available later. A fee-free advance can remain difficult if the repayment timing collides with another essential bill.
Before requesting money, I recommend writing down three things: the amount needed, the date the money must arrive, and the exact amount that can be repaid without creating another emergency. That small check is more valuable than rushing through an application. The app may help solve today’s problem, but it cannot make an unaffordable repayment schedule affordable.
Compared with a credit card, the main advantage is simplicity for someone who wants to avoid revolving debt and interest charges. Compared with overdraft protection, it may feel more deliberate because the user actively seeks an advance instead of allowing an account balance to fall below zero. Compared with borrowing from a friend or family member, it offers more privacy and less social pressure. On the other hand, a trusted person may be more flexible about timing, while a bank account buffer or savings account is usually safer when one is available.
What the current version tells me about the product
The current release is version 2.67.1406, and the app supports Android 7.0 or later. That broad compatibility matters for people using older phones, especially those who cannot replace a device simply to access a financial service. The app was released on December 15, 2023, so it is not an old product being maintained only in name. Its current version number also indicates an ongoing development path rather than a one-time launch.
I see that evolution as useful in a finance app because trust depends heavily on a stable, understandable experience. A cash advance service has to make the important steps easy to follow: checking eligibility, reviewing the amount, understanding repayment, and knowing what happens after confirmation. Small improvements in navigation or clarity can matter more here than flashy additions. When money is tight, uncertainty is a form of friction.
At the same time, a version number alone does not tell me that every user will have the same result. Eligibility, available amount, and delivery timing can depend on personal circumstances and account details. I would not treat the app’s general promise as a guarantee that a request will be approved or that funds will arrive at the exact moment an emergency begins. The responsible approach is to use it as one possible option, not as money that is already in hand.
The app’s rating, now around 4.8, is encouraging, and the number of written reviews is close to 8.9 thousand. I read that kind of response as evidence that the basic concept works well for many users. Still, financial apps often receive very different reactions depending on an individual’s eligibility, repayment date, bank connection, and expectations. A positive average cannot replace reading the terms shown during the actual request.
What existing users may notice after updates
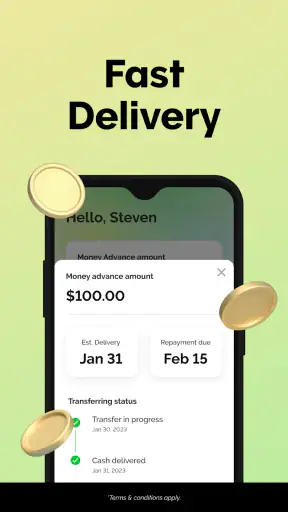
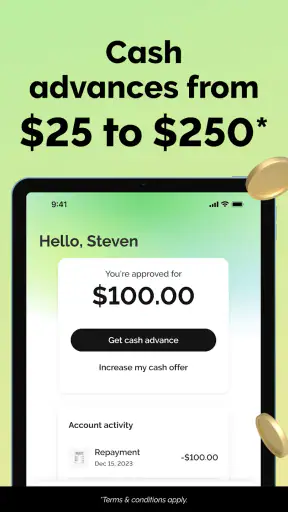
For someone returning to the app, the most meaningful change is likely not a dramatic new feature but a smoother path through the core task. With a product like this, returning users benefit when the dashboard makes the current status obvious and reduces the number of decisions required to understand an advance. I would pay attention to whether the latest version presents the repayment obligation as clearly as the amount being offered. A fast request is only genuinely helpful when the follow-through is equally transparent.
My practical advice is to update before an emergency rather than during one. That gives you time to sign in, review the available screens, check how repayment is displayed, and make sure your account information is current. It also prevents a last-minute update from becoming another delay. I would not request an advance simply to test the app, but setting it up calmly can show whether it fits your needs before the pressure is real.
Existing users should also keep their own record of the transaction. I would save the confirmation details, note the expected repayment date in a calendar, and compare the amount with my personal budget rather than relying only on memory. This is especially useful if the advance is taken for an expense that will recur, such as transportation or household supplies. A private note can make the difference between a one-off bridge and a cycle that becomes hard to control.
Another useful habit is separating the reason for the advance from the convenience of access. If the app makes funds feel easy to request, that convenience can encourage a larger amount than necessary. I would request only what closes the specific gap. For example, if a bill is short by a small amount, borrowing extra for discretionary spending weakens the whole point of using a short-term tool.
Where the app still needs careful handling
The biggest limitation is inherent to the product category: quick access can encourage quick decisions. The phrase “no interest” may sound like there is no financial downside, but repayment still has to happen. I would read every screen before accepting an advance, paying special attention to the total repayment amount, timing, and any conditions attached to the request. If those details are not immediately understandable, I would pause rather than assume.
Another gap is that a cash advance does not solve irregular income or persistent debt. Someone whose paycheck changes from week to week may need a broader budgeting service, a conversation with a creditor, or help from a nonprofit financial counselor. Someone carrying balances on high-cost credit may be better served by a repayment plan or lower-cost consolidation option. Grant Cash Advance can be useful for a narrow cash-flow problem, but it is not a complete financial plan.
I also would not choose it as the first option for a large expense. A larger purchase deserves time to compare personal loans, credit union products, employer assistance, payment plans, or savings strategies. Those alternatives may involve more paperwork, but that extra effort can be worthwhile when the amount is significant. The convenience of a fast app is most valuable when the need is small and the repayment path is already clear.
People who dislike linking financial services, reviewing eligibility information, or managing repayment reminders may find the experience less comfortable than expected. The app is designed to shorten the path to an advance, but users still need to take responsibility for the details. I would also skip it if I could not explain how repayment would affect my next budget. That is a simple test, and failing it is a strong reason to look for another solution.
Age access is broad because the content rating is Everyone, but that should not be read as financial advice for every household. Younger users and anyone sharing financial responsibilities should discuss the repayment effect with the person who manages the budget. A service being easy to access does not make the decision consequence-free.
Practical ways to use it without losing control
My preferred workflow starts outside the app. I identify the exact expense, check the due date, and calculate what will remain after repayment. Then I open the app and compare the available advance with that prewritten figure. This prevents the amount displayed by the service from becoming the amount I automatically choose. It also makes the decision less emotional when the expense is urgent.
I would use a separate calendar reminder for the repayment date, even if the app already shows it. The reminder should be placed several days ahead, giving me time to check the linked account and move money if needed. This is a small but non-obvious safeguard: the advance solves the immediate shortage, while the reminder protects against forgetting the later obligation.
For a recurring expense, I would treat the first advance as a diagnostic rather than a routine. If I need help with the same bill again, I would review the previous month’s spending before requesting another amount. That can reveal whether the problem was a one-time timing issue or a structural gap. In the first case, the app may remain a reasonable bridge; in the second, repeating the process is likely to make the budget more fragile.
I would also compare the app with the alternatives based on urgency, not just advertised cost. A no-interest advance may be preferable to an overdraft or a costly card balance when the repayment date is certain. A savings transfer is better when it does not leave the account unable to cover essentials. A payment extension is better when the provider offers one without harmful consequences. The right choice depends on which option creates the least future pressure, not merely which one feels fastest today.
Who should consider it and who should look elsewhere
I can recommend Grant Cash Advance to someone facing a short, well-defined gap who wants to avoid a credit check and interest. It is particularly appealing when the user has a specific repayment date, understands the amount being requested, and needs a simpler alternative to a credit card. The free entry point and support for older Android devices make it easy to investigate without a financial commitment just to download the app.
I would be more cautious with anyone already relying on advances to reach each payday. In that situation, the app may provide temporary relief while leaving the main issue untouched. A bank hardship program, employer-based advance, community resource, credit counselor, or carefully compared loan may be more appropriate. Someone who needs a large amount should also compare longer-term options rather than assuming a cash advance is automatically the cheapest or safest route.
The app is also not ideal for a purchase that can wait. If the expense is optional, delaying it is usually better than introducing another repayment obligation. I would reserve this kind of service for necessities or time-sensitive costs, not for impulse shopping, entertainment, or an upgrade that can be planned later.
What I would watch before relying on it
As the product continues to evolve, I would watch how clearly each release explains the user’s obligations. In a finance app, clearer repayment displays, better status information, and fewer ambiguous steps are more important to me than cosmetic changes. I would also look for a consistent explanation of eligibility and delivery expectations so users do not mistake a general promise for a guaranteed outcome.
I would keep an eye on the balance between speed and safeguards. The best experience is not necessarily the one with the fewest taps; it is the one that lets a user move quickly while still understanding the consequences. If future updates make the request process faster, I hope they preserve prominent information about repayment and encourage users to borrow only what they need.
My overall view is positive but deliberately limited. This is a useful bridge for a specific cash-flow emergency, not a substitute for savings or a stable budget. Kikoff Inc. has built an accessible finance app with a clear appeal, and the current version shows that the product is still being maintained and developed. I would keep it available as one option, prepare my repayment plan before requesting anything, and choose a different financial route whenever the problem is larger, recurring, or unclear.
After using it with that mindset, I think the app is worth considering for the right person. Its value comes from matching a narrow need: a short-term shortage that can be repaid without creating another one. If that describes your situation, the free app gives you a convenient place to explore the option. If it does not, the most responsible decision may be to leave it unused and focus on a solution that addresses the underlying budget instead.


